For HR and payroll teams, some regulatory changes look small on paper and then create a surprisingly long to-do list. The latest ₹25,000 wage ceiling is one of those changes.
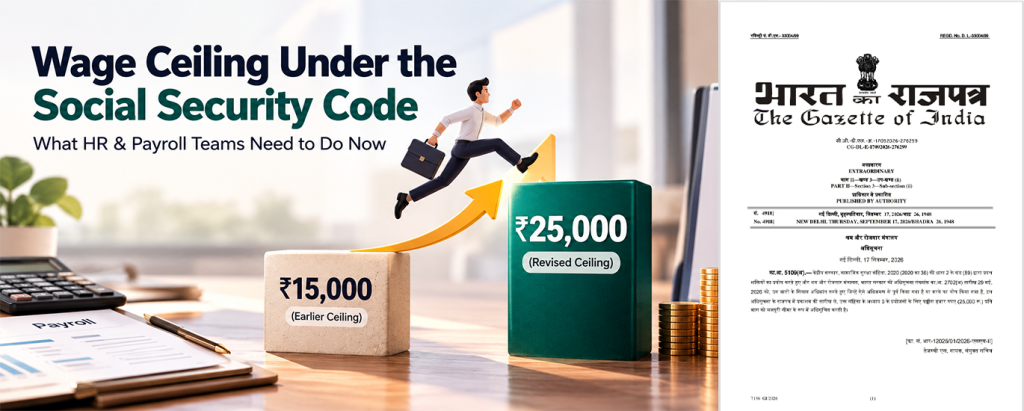
On 17 September 2026, the Ministry of Labour and Employment notified a revised wage ceiling of ₹25,000 per month for the purposes of Chapter III of the Code on Social Security, 2020. This replaces the earlier ₹15,000 ceiling notified in May 2026. The change is effective from the date of publication in the Official Gazette.
The important point for HR teams is that this isn’t simply a number to replace in a payroll spreadsheet. It can affect employee coverage, contribution calculations, payroll configuration, onboarding, employee communication and compliance processes.
And if your organisation has a sizeable group of employees earning between ₹15,000 and ₹25,000 a month, now is a good time to stop treating this as a “next payroll cycle” task.
What Has Actually Changed?
The ceiling has moved from ₹15,000 to ₹25,000:
The government has notified ₹25,000 per month as the wage ceiling for Chapter III of the Social Security Code. The earlier notification had prescribed ₹15,000. For employees who fall within the relevant coverage conditions, the higher ceiling expands the pool that can come under mandatory EPFO-linked social security coverage.
The change is effective from 17 September 2026:
This isn’t a proposal waiting for another effective date. The notification was published on 17 September and states that the new ceiling takes effect from the date of publication. That means payroll teams need to review their treatment from September itself rather than casually pushing the change into a later financial year.
Employees between ₹15,000 and ₹25,000 are the key group:
This is where HR teams should begin their employee-level review. Someone earning ₹18,000 or ₹22,000 who was previously outside mandatory coverage solely because their wages exceeded ₹15,000 may now fall within the revised threshold, subject to the applicable provisions and scheme rules. The government estimates that more than 51 lakh additional employees could come under mandatory EPFO coverage.
It is specifically linked to Chapter III:
One detail that can easily get lost in headlines is that the notification is for Chapter III of the Code, which deals with provident fund-related social security. It shouldn’t be casually read as a ₹25,000 universal wage threshold for every benefit under the entire Social Security Code. HR teams should continue checking the specific eligibility rules applicable to each social-security benefit.
Why Payroll Teams Shouldn’t Just Change the Number
Payroll logic may be built around ₹15,000:
Many payroll systems have statutory rules embedded into salary calculations. If the system has a hard-coded PF ceiling, changing the policy document won’t automatically change the calculation engine. A payroll administrator may need to update configuration, run test calculations and verify the resulting employee and employer contributions before the live payroll is processed.
Employee deductions can change:
Where contributions are calculated against the revised ceiling, the employee’s PF deduction can increase. For example, a 12% employee contribution on ₹15,000 is ₹1,800, whereas 12% on ₹25,000 is ₹3,000. The actual treatment, however, depends on the employee’s coverage, wage definition and applicable scheme provisions.
Employer cost needs to be recalculated:
This is the part finance teams will notice quickly. A higher contribution base can increase the employer’s statutory outgo for affected employees. If an organisation has hundreds of employees in the ₹15,000–₹25,000 bracket, what looks like a few hundred rupees per employee can become a meaningful monthly payroll cost.
Don’t forget the EPS component:
The government’s clarification notes that, where applicable, the maximum EPS contribution can now be calculated at 8.33% of ₹25,000 rather than ₹15,000. That changes the maximum pension contribution from roughly ₹1,250 to about ₹2,083 per month. Payroll configurations should therefore be tested for both EPF and EPS treatment rather than checking only the employee PF deduction.
The First HR Task: Identify the Affected Employees
Run a salary-band report:
Start with a simple employee population report. Pull everyone whose relevant monthly wages fall between ₹15,000 and ₹25,000 and separate them from employees already covered under EPFO. This immediately gives HR a practical working list instead of making the entire payroll population part of the exercise.
Separate new joiners from existing members:
Not every employee sitting below ₹25,000 should automatically be treated as a completely new case. Existing EPFO members generally continue to remain members even when their wages change. The important review is how the revised ceiling affects employees who were previously excluded because of the old threshold and how existing contribution arrangements should be treated.
Check the reason for previous exclusion:
Don’t rely only on salary figures. Someone earning ₹24,000 might have been excluded for a reason that isn’t simply the old ₹15,000 threshold. HR should verify the employee’s historical PF status and applicable eligibility conditions before changing records.
Include contract labour in the review:
This is an easy area to miss. Organisations often focus on their direct employees and forget that statutory social-security compliance can have implications for contract labour as well. EY specifically recommends that employers assess the impact of the revised wage ceiling on their contract workforce.
Payroll Systems Need a Proper Test Run
Update the statutory configuration:
If your payroll software has a statutory ceiling field, contribution rule or employee eligibility parameter, review it carefully. Don’t simply overwrite “15,000” with “25,000” and assume everything is finished. The system may have separate settings for employee contribution, employer contribution, EPS, eligibility and reporting.
Run parallel calculations:
Before processing the live payroll, take a sample group and calculate the old and revised amounts. For example, test employees earning ₹17,000, ₹20,000, ₹24,000 and ₹25,000. This makes it much easier to spot a configuration problem before it reaches payslips.
Check rounding and statutory reports:
A payroll system can calculate the correct headline contribution while producing an incorrect statutory report because of a separate configuration. ECR-related data, contribution amounts, employee status and payroll registers should all be checked during testing.
Review the September payroll treatment:
Since the notification is effective from 17 September 2026, payroll teams should specifically establish how their September payroll will reflect the change. Whether an organisation has already processed payroll or is still running it can make the practical handling different, so the implementation approach should be documented rather than improvised at the last minute.
HR Communication Matters More Than It Looks
Employees may notice a lower take-home salary:
If an employee’s PF deduction increases, the first reaction may simply be, “Why did my salary reduce this month?” That’s completely understandable. A short explanation on the payslip or through an HR communication can prevent dozens of repetitive payroll queries.
Explain the retirement benefit angle:
The additional deduction isn’t simply disappearing from the employee’s salary. Where applicable, higher PF contributions can build a larger retirement corpus over time, while EPS and EDLI-related benefits are also part of the statutory framework. The exact benefit depends on the employee’s circumstances and applicable scheme rules.
Use an actual salary example:
Employees understand numbers faster than legal language. For instance, if an eligible employee’s contribution is calculated at 12% of ₹25,000, the employee-side PF amount would be ₹3,000. Showing this alongside the previous ₹1,800 figure makes the change much easier to understand.
Train payroll helpdesk teams first:
There’s little point sending a detailed HR email if the payroll helpdesk gives three different answers afterward. Give HR executives and payroll representatives a simple FAQ covering eligibility, deductions, effective date and the likely impact on take-home pay.
Review CTC and Employer Cost Before the Next Budget Cycle
Recalculate employee-level CTC:
Companies that structure compensation with employer PF as part of CTC should revisit their calculations. A statutory contribution increase can affect the relationship between gross salary, employer contribution and total CTC, particularly for employees who were previously outside mandatory coverage.
Model the monthly financial impact:
Suppose an organisation has 200 affected employees. Even a few hundred rupees of additional employer cost per employee can become a substantial annual amount. Finance and HR should therefore calculate the impact employee-by-employee instead of using a broad percentage assumption.
Review salary offers in progress:
This is especially relevant for HR teams currently making offers in the ₹15,000–₹25,000 range. If an offer was prepared before the notification and assumed a different PF treatment, the CTC and take-home figures may need to be recalculated before the candidate joins.
Don’t confuse CTC with take-home pay:
This is where employee conversations can get messy. An increase in employer statutory contribution may affect CTC, while an increase in employee contribution can affect monthly take-home pay. They aren’t the same thing, and HR should explain the distinction clearly.
Keep an Eye on Scheme-Specific Clarifications
The wage ceiling notification isn’t the whole story:
The 17 September notification sets the ₹25,000 ceiling for Chapter III purposes. It doesn’t mean every individual EPF, EPS or EDLI provision has automatically been rewritten by that one notification. Employers should therefore avoid making assumptions where a scheme-specific rule or subsequent clarification is required.
Watch official EPFO communications:
Payroll teams should keep checking official Ministry of Labour and EPFO communications for operational instructions, especially around enrolment, contribution filing and reporting. The practical implementation details matter just as much as the headline change.
Document your interpretation:
This sounds boring, but it saves trouble later. Keep a copy of the notification, internal payroll interpretation, configuration changes, test results and approval trail. If someone asks six months later why a particular employee was enrolled or why a contribution changed, the payroll team shouldn’t have to reconstruct the decision from memory.
Escalate unusual cases:
Employees with historical higher-wage contributions, special membership circumstances, exempted establishments or unusual salary structures may not fit neatly into the standard payroll rule. Those cases deserve individual review rather than forcing them through an automated assumption.
A Practical HR & Payroll Checklist
Employee mapping:
Prepare a list of employees in the ₹15,000–₹25,000 wage range and identify which employees were previously outside EPFO coverage because of the old ceiling. Cross-check their existing membership and employee records before making changes.
System configuration:
Review PF, EPS and related payroll parameters, update the applicable ceiling, and test multiple salary cases. Save the test output so that payroll and finance teams can sign off on the change.
Cost impact:
Calculate the additional employee deductions and employer contributions. Finance should ideally see the monthly and annual impact before the revised payroll is finalised.
Compliance filing:
Verify employee enrolment, Aadhaar/KYC information where required, contribution calculations and statutory filing data. Recent EPFO guidance highlighted the need for establishments to update payroll systems, enrol eligible workers and file timely ECRs.
Employee communication:
Prepare a short FAQ explaining what changed, who is affected and why take-home salary may change. Keep the language simple. Employees don’t need a 20-page legal note to understand a ₹1,000 difference in their payslip.
The ₹25,000 ceiling may look like a straightforward revision from one number to another. For HR and payroll teams, though, it touches several moving parts at once employee eligibility, contribution calculations, payroll software, CTC, statutory filings and employee communication.
The teams that handle it well won’t necessarily be the ones who make the biggest announcement. They’ll be the ones who quietly check the employee list, test the payroll calculations, document the change and make sure nobody discovers a compliance issue through a rejected return or a confused payslip.
And honestly, that’s usually what good payroll work looks like: most people never notice it when everything is done properly.